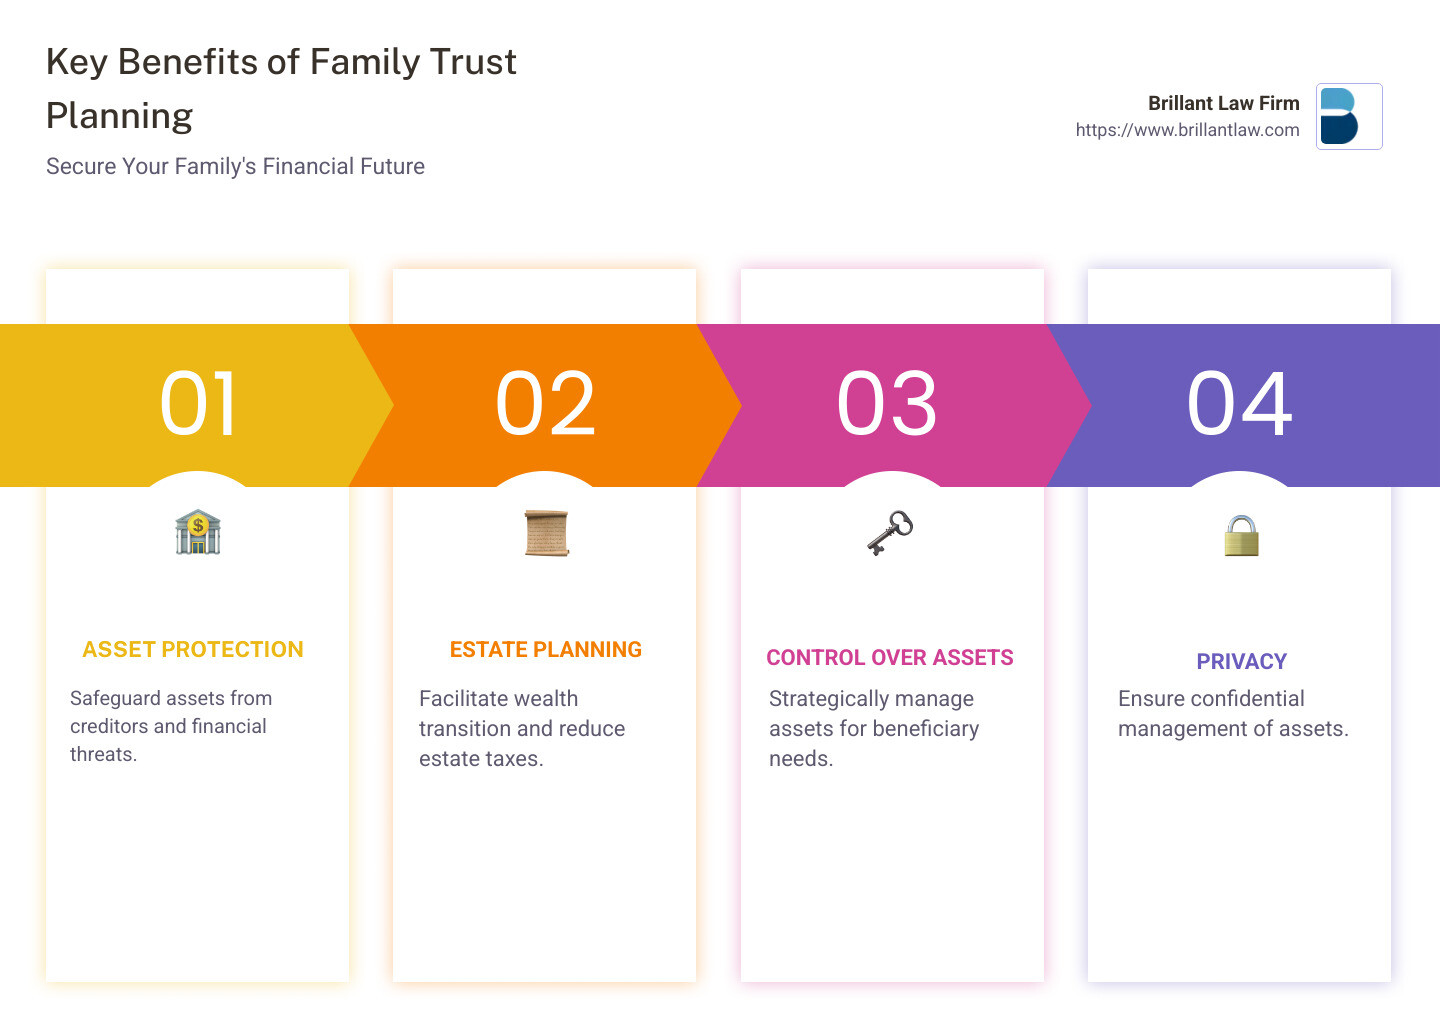
Family trust planning is essential for those looking to secure their family’s financial future, streamline estate management, and preserve wealth across generations. Here’s a quick snapshot of why it’s important:
- Asset Protection: Protect family assets from creditors and financial vulnerabilities.
- Estate Planning: Facilitate wealth transition and potentially reduce estate taxes.
- Control Over Assets: Enable strategic asset management for specific beneficiary needs.
- Privacy: Ensure confidential management and allocation of assets.
Family trust planning is crucial in optimizing estate distribution, enhancing tax benefits, and safeguarding your family’s financial stability.
As someone deeply experienced in this field, I’m David Brillant, a Certified Specialist in Estate Planning, Trust, and Probate Law in California. I’ve steerd numerous complex estate scenarios to provide custom solutions. Let’s explore together how family trust planning can be your ally in securing the wealth you’ve built.
Understanding Family Trusts
When it comes to Family Trust Planning, understanding the key players and types of trusts is crucial. Let’s break it down.
Key Players in a Family Trust
Grantor: The grantor, sometimes called the settlor, is the person who creates the trust. They transfer assets into the trust to be managed for the benefit of others.
Trustee: The trustee is responsible for managing the trust according to the grantor’s wishes. They have a fiduciary duty, meaning they must act in the best interest of the beneficiaries. Trustees can be individuals or professional entities. It’s a role requiring trust and reliability.
Beneficiaries: These are the family members who benefit from the trust. They receive the assets or income, as specified in the trust agreement, after the grantor’s passing.
Types of Family Trusts
Revocable Trusts
A revocable trust offers flexibility. As the name suggests, the grantor can modify or revoke the trust during their lifetime. This means you can adjust terms or beneficiaries as circumstances change. It’s a popular choice because it avoids probate, keeping your estate matters private and efficient.
- Control: The grantor retains control over the assets.
- Privacy: Assets in a revocable trust are not subject to public probate.
- Flexibility: Modify or dissolve the trust as needed.
Irrevocable Trusts
On the flip side, an irrevocable trust cannot be changed once it’s established. This type is often used for tax benefits and asset protection because the assets are no longer considered part of the grantor’s estate.
- Tax Benefits: Assets are not subject to estate taxes.
- Protection: Shields assets from creditors.
- Permanence: Once set, it cannot be altered without the beneficiaries’ consent.
Why Choose a Family Trust?
Family trusts can be a powerful tool in estate planning. They provide a structured way to manage and distribute your assets while ensuring your wishes are respected. By understanding the roles of the grantor, trustee, and beneficiaries, as well as the types of trusts available, you can make informed decisions that align with your family’s needs.
In the next section, we’ll dive into the benefits of family trust planning and how it can help you avoid probate, minimize estate taxes, and more.
Benefits of Family Trust Planning
Family trusts are not just about passing on wealth; they offer several strategic advantages that can simplify and improve estate management. Let’s explore some key benefits of Family Trust Planning.
Avoid Probate
One of the most significant advantages of setting up a family trust is avoiding probate. Probate is the legal process that occurs after someone passes away, where the court oversees the distribution of the deceased’s estate. This process can be lengthy, expensive, and public.
By placing assets in a trust, you ensure they are transferred directly to beneficiaries without court intervention. This not only speeds up the process but also keeps your family’s financial matters private.
Minimize Estate Taxes
Family trusts can be a powerful tool for minimizing estate taxes. By strategically placing assets in an irrevocable trust, you can remove them from your taxable estate. This means they won’t be subject to estate taxes upon your passing, potentially saving a significant amount of money.
For high-net-worth individuals, utilizing a family trust can be a smart way to leverage the current tax exemptions and protect more of your wealth for future generations.
Maintain Privacy
Privacy is a crucial concern for many families. Unlike a will, which becomes public record once it goes through probate, a trust remains private. This means that the details of your estate and its distribution stay confidential, known only to the involved parties.
This level of privacy can prevent unwanted scrutiny and protect your family’s financial matters from becoming public knowledge.
Increase Flexibility
A well-structured family trust offers flexibility in managing and distributing assets. With a revocable trust, you can make changes as your circumstances evolve, such as adjusting beneficiaries or modifying terms. This adaptability ensures that the trust aligns with your current wishes and family dynamics.
Even irrevocable trusts, while more rigid, can be crafted with specific clauses that allow for certain adjustments under predefined conditions.
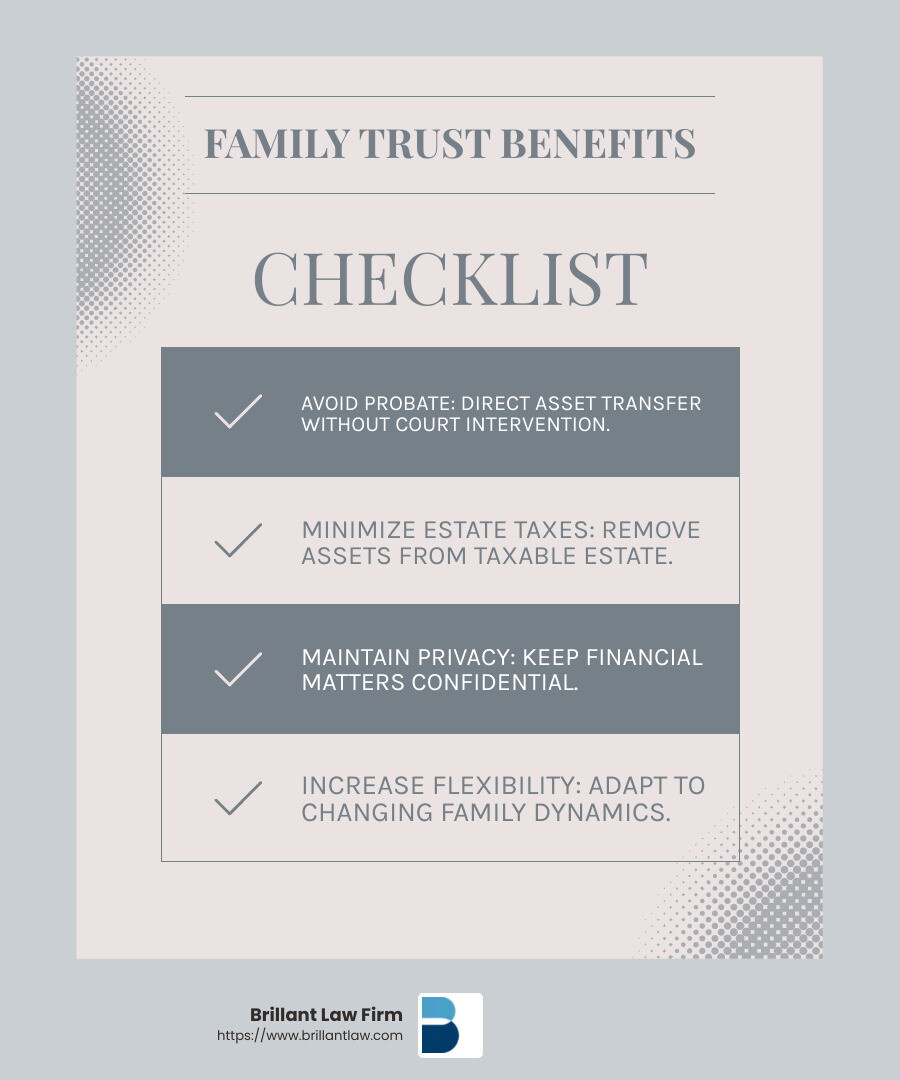
Family trusts provide a robust framework for managing your estate, offering benefits like avoiding probate, minimizing taxes, maintaining privacy, and increasing flexibility. By understanding these advantages, you can make informed decisions that align with your family’s needs and goals.
In the next section, we’ll explore the different types of family trusts and how to choose the right one for your situation.
Types of Family Trusts
When it comes to Family Trust Planning, understanding the different types of trusts is crucial. Each type serves a unique purpose and offers specific benefits. Let’s explore the most common types of family trusts.
Revocable Trusts
A revocable trust is like a flexible toolbox for your estate. You can change it, add to it, or even dissolve it during your lifetime. This flexibility makes it a popular choice for those who want control over their assets. Revocable trusts are perfect for adapting to life changes like marriage, divorce, or the birth of a child.
“A revocable trust is like having a safety net you can adjust,” says an estate planning expert.
However, because you retain control, the assets in a revocable trust are still considered part of your estate for tax purposes.
Irrevocable Trusts
Unlike revocable trusts, irrevocable trusts are set in stone once created. You can’t change or cancel them without the beneficiary’s consent. This might sound limiting, but it offers significant advantages. Assets in an irrevocable trust are removed from your estate, which can help reduce estate taxes and protect assets from creditors.
Irrevocable trusts are ideal for those who are confident in their decisions and want to secure their assets for future generations.
Spendthrift Trusts
A spendthrift trust is designed to protect beneficiaries from themselves. It limits how and when they can access trust assets. This is especially useful if a beneficiary struggles with managing money or has creditors chasing them. The trust ensures they receive support without the risk of squandering their inheritance.
By setting specific terms, you can control the flow of funds, ensuring long-term financial security for your loved ones.
Special Needs Trusts
A special needs trust is a lifeline for individuals with disabilities. It provides financial support without affecting their eligibility for government benefits like Medicaid or SSI. This trust ensures that your loved one has the resources they need for a better quality of life while maintaining access to crucial assistance programs.
“A special needs trust is a compassionate choice for families,” notes a California estate planning attorney.
Bypass Trusts
A bypass trust, also known as an AB trust, is a strategic tool for married couples. When one spouse passes away, their share of the estate goes into the bypass trust. The surviving spouse can use the income from the trust, but the principal is preserved for the children or other beneficiaries. This helps minimize estate taxes and ensures that the estate is passed on according to the couple’s wishes.
Each type of trust offers unique benefits and can be custom to fit your family’s needs. Understanding these options is the first step in making informed decisions about your family’s financial future.
Next, we’ll discuss how to set up a family trust in California, ensuring your assets are protected and your wishes are honored.
Setting Up a Family Trust in California
Creating a family trust in California is a strategic way to manage and protect your assets. Here’s a step-by-step guide to help you through the process:
Choose the Right Trust Type
The first step in Family Trust Planning is deciding which type of trust fits your needs. Do you want the flexibility of a revocable trust, or the tax benefits of an irrevocable trust? Consider your family’s unique situation and future needs.
“Choosing the right trust is like picking the right tool for the job,” says a seasoned estate planner.
Draft the Trust Document
Once you’ve chosen the trust type, it’s time to draft the trust document. This legal document outlines the trust’s terms, including:
- Grantor: The person setting up the trust.
- Trustee: The person or entity managing the trust.
- Beneficiaries: The family members or entities benefiting from the trust.
- Assets: Detailed list of assets included in the trust.
- Terms and Conditions: How and when assets will be distributed.
Working with an experienced estate planning attorney in California is crucial. They ensure the document meets state requirements and reflects your wishes accurately. Expect to pay between $2,500 and $5,000 for this service.
Sign the Trust
After drafting, the trust document must be signed according to California state laws. This typically involves notarization and possibly witnesses, depending on the trust type. A small error here can cause big headaches later, so attention to detail is key.
Transfer Assets into the Trust
Finally, transfer assets into the trust’s name. This can include:
- Bank Accounts
- Investment Accounts
- Real Estate
By transferring assets, you legally shift ownership to the trust. This step is crucial; without it, the trust can’t function as intended.
“Think of asset transfer as moving your valuables into a safe. The trust is the safe,” explains a California legal expert.
Setting up a family trust might seem daunting, but with careful planning and professional guidance, you can secure your family’s future. Now, let’s address some common questions about family trusts to further clarify the process.
Frequently Asked Questions about Family Trust Planning
What is the downside of a family trust?
While family trusts offer many benefits, they do come with some downsides. One major concern is rigidity and inflexibility. Once a trust is established, especially an irrevocable one, altering its terms can be challenging. This means any changes in family dynamics or financial situations may not be easily accommodated.
Additionally, family trusts can be costly to set up and maintain. In California, legal fees for drafting a trust can range from $2,500 to $5,000, and managing the trust may incur ongoing expenses. Trusts also require diligent administrative work, which can be time-consuming.
What is the best structure for a family trust?
Choosing between a revocable and irrevocable trust largely depends on your goals. A revocable trust offers flexibility. You can modify its terms or even dissolve it if your circumstances change. This makes it a popular choice for those who want to maintain control over their assets during their lifetime.
On the other hand, an irrevocable trust cannot be easily altered once established. While this may seem limiting, it offers significant tax advantages and better protection from creditors. It’s ideal for those looking to reduce estate taxes or protect assets from potential legal claims.
“Think of a revocable trust as a living document you can change, while an irrevocable trust is like cement—solid but permanent,” notes a California estate planning expert.
What is the biggest mistake parents make when setting up a trust fund?
One of the most common mistakes is choosing the wrong trustee. The trustee is responsible for managing the trust and making decisions that affect its beneficiaries. If a trustee lacks the necessary skills or integrity, it can lead to mismanagement of the trust assets, potentially depleting the resources intended for your family.
To avoid this, it’s crucial to select a trustee with a strong track record of financial acumen and ethical standards. Professional trustees or trust companies can be a good option if you don’t have a suitable individual in mind.
“Selecting the right trustee is paramount. It’s like choosing a captain for your ship; their expertise can steer your family’s future in the right direction,” advises a seasoned legal advisor.
Understanding these aspects of family trust planning can help you make informed decisions that align with your family’s needs and goals. As you steer this process, keep these considerations in mind to ensure your trust serves its intended purpose effectively.
Conclusion
At Brillant Law Firm, we understand that family trust planning is not just about managing assets; it’s about securing your family’s future. Our commitment to providing bespoke strategies custom to each client’s unique needs sets us apart. With our deep expertise in California estate planning, we ensure that your family trust is not only effective but also adaptable to life’s changes.
Creating a family trust can be a complex process. However, with the right guidance, it becomes a powerful tool for protecting your assets and ensuring your wishes are honored. Whether you’re looking to avoid probate, minimize estate taxes, or maintain privacy, our team specializes in crafting strategies that align with your goals.
Our attorneys are well-versed in the nuances of California law, ensuring that your trust complies with all state requirements. We take pride in offering personalized service, working closely with you to develop a plan that reflects your family’s values and future aspirations.
Choosing the right partner for your estate planning needs is crucial. At Brillant Law Firm, we combine unparalleled expertise with unwavering dedication to help you steer the complexities of family trust planning. Let us be your guide in securing your family’s legacy.
For more information on setting up a living trust, visit our Living Trust Setup page.