
Estate planning guidance is vital for ensuring that your wishes for asset distribution are honored and your loved ones are taken care of, giving you peace of mind. Here’s a quick guide to the essentials:
- Assemble a team of professionals, including an estate planning attorney.
- Create vital documents: wills, trusts, power of attorney, and healthcare directives.
- Determine guardians for dependents and an executor for your estate.
- Plan for potential incapacity with advance directives.
Estate planning isn’t just about writing a will; it involves organizing your entire estate to safeguard it against undue taxation, legal battles, and ensures your values are maintained. By focusing on the seamless transfer of assets and minimizing government intervention, you can leave a lasting legacy.
As a seasoned expert in this field, I am David Brillant, a certified estate planning, trust, and probate law specialist in California, dedicated to providing personalized estate planning guidance. With years of experience, I understand the complexities and nuances involved in crafting robust, client-focused estate plans.
Understanding Estate Planning
Estate planning is the process of arranging how your assets will be managed and distributed after your death or in case you become incapacitated. It’s not just for the wealthy; everyone can benefit from it. The goal is to ensure your assets go to the right people, with minimal legal hassle and tax implications.
Key Elements of Estate Planning
Wills: This is a legal document that spells out your wishes regarding asset distribution and guardianship of minor children. It’s a fundamental part of estate planning but not the only element.
Trusts: A trust is a legal entity that holds assets on behalf of your beneficiaries. Trusts can help avoid probate, reduce estate taxes, and provide more control over when and how your assets are distributed.
Power of Attorney: This document allows someone you trust to manage your financial affairs if you’re unable to do so. It’s crucial for managing your estate during your lifetime.
Healthcare Directives: These are instructions for your medical care if you can’t communicate your wishes. They ensure that your healthcare preferences are respected.
Asset Management
Managing your assets involves organizing everything you own—from real estate and stocks to personal items and debts. The main goal is to ensure these are handled according to your wishes, both during your life and after.
Inventory Your Assets: Start by listing everything you own and owe. This includes properties, investments, bank accounts, insurance policies, and personal belongings.
Organize Your Documents: Keep all important documents, like deeds, titles, and account statements, in a safe place. Make sure your executor or trusted family member knows where to find them.
Review and Update Regularly: Life changes, and so should your estate plan. Regular updates ensure that your plan reflects your current wishes and circumstances.
Minimize Taxes: Use strategies like setting up trusts or making charitable donations to reduce your estate’s tax burden.

Estate planning is about more than just legal documents. It’s about ensuring your legacy is protected and your loved ones are cared for, with minimal stress and confusion. With the right estate planning guidance, you can craft a plan that honors your wishes and secures your family’s future.
Next, we’ll explore how to avoid probate in California, saving your heirs time and money while ensuring a smoother transition of your assets.
Essential Estate Planning Documents
When it comes to estate planning guidance, having the right documents in place is crucial. These documents ensure your wishes are respected and can save your loved ones from unnecessary stress. Here’s a breakdown of the essential documents you need:
Wills
A will is the cornerstone of any estate plan. It outlines how you want your assets distributed after your death and can also name guardians for minor children. Without a will, the state of California will decide how to distribute your assets, which might not align with your wishes.
Pro Tip: Review your will regularly, especially after major life events like marriage, divorce, or the birth of a child.
Trusts
Trusts are powerful tools that can help manage your estate and avoid probate. They can be particularly useful in California, where probate can be lengthy and costly. A trust allows you to specify how and when your assets are distributed, providing more control and potentially reducing estate taxes.
Example: Aretha Franklin’s estate faced turmoil due to unclear estate planning. A properly structured trust might have helped avoid such issues.
Power of Attorney
A power of attorney (POA) allows someone you trust to manage your financial affairs if you’re unable to do so. This document is crucial for handling your estate during your lifetime, especially in cases of incapacity.
Consideration: Choose someone responsible and trustworthy, as they will have significant control over your financial matters.
Healthcare Directives
Healthcare directives, also known as living wills or advance directives, outline your medical care preferences if you’re unable to communicate them. This document ensures that your healthcare choices are respected, even if you can’t voice them yourself.
Real-Life Insight: As life expectancy increases, so does the likelihood of needing long-term care. A healthcare directive can provide peace of mind that your medical wishes will be honored.
These documents form the foundation of a solid estate plan. They help ensure your assets are distributed according to your wishes and that your healthcare preferences are respected. Next, we’ll dive into how to avoid probate in California, a crucial step in streamlining the estate transition process.
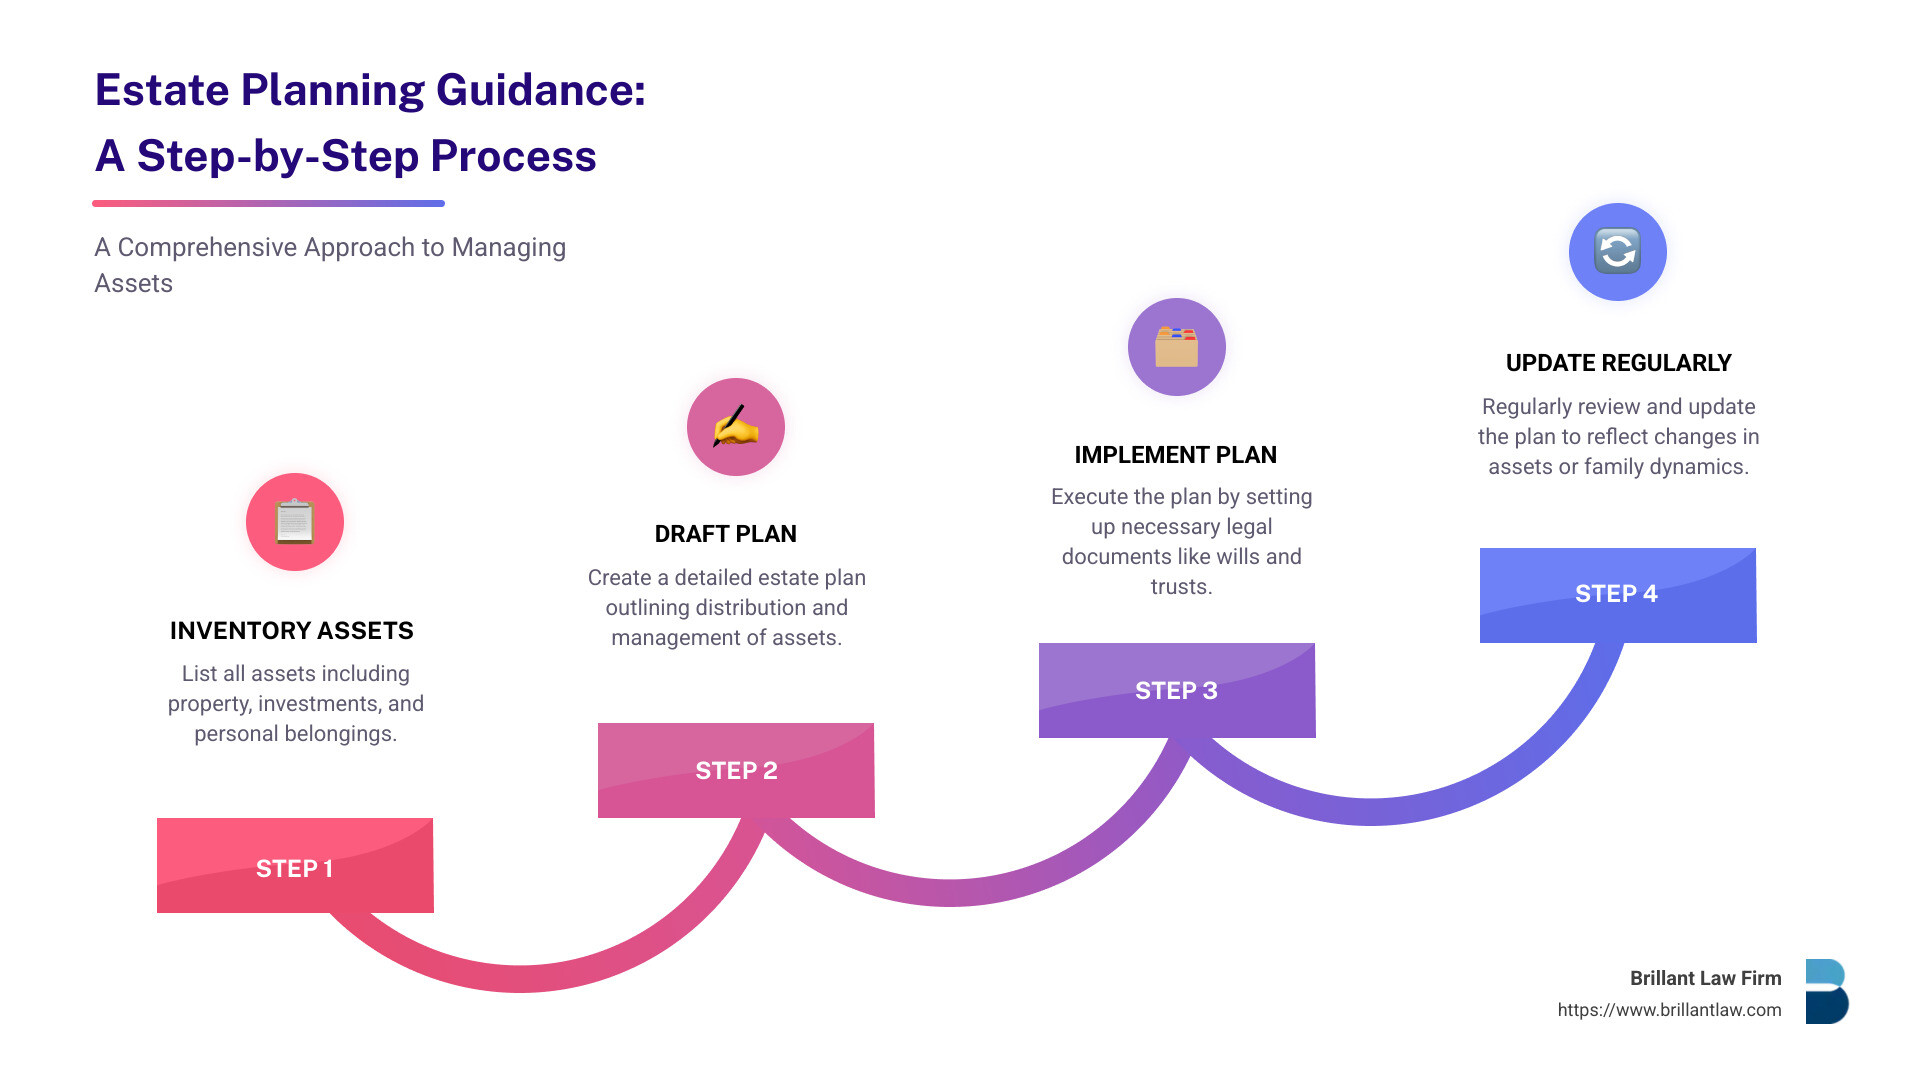
Estate Planning Guidance: A Step-by-Step Process
Estate planning doesn’t have to be overwhelming. With the right guidance, you can create a solid plan that ensures your wishes are followed. Here’s a simple, step-by-step guide to help you through the process.
1. Inventory Your Assets
Start by listing everything you own. This includes your home, cars, jewelry, and even smaller items like electronics. Don’t forget about non-physical assets like bank accounts, stocks, and life insurance policies.
Tip: Use an Asset Inventory worksheet to keep everything organized. This will help you see the full picture of your estate and make informed decisions.
2. Draft Your Plan
Once you know what you have, think about how you want to distribute your assets. Consider who will inherit your belongings, who will care for any minor children, and who will manage your affairs if you can’t.
Pro Tip: It’s wise to consult with an estate planning attorney in California. They can provide valuable insights and help draft documents that reflect your wishes.
3. Implement Your Plan
With your plan in place, it’s time to make it official. Work with your attorney to create a will, trusts, and any other necessary documents. Ensure all assets you want in a trust are retitled correctly.
Remember: If you set up a trust, fund it promptly. An unfunded trust won’t serve its purpose, and your assets might not end up where you intend.
4. Update Regularly
Life changes, and so should your estate plan. Review your documents regularly, especially after significant life events like marriage, divorce, or the birth of a child.
Fact: About 46% of Americans don’t have a will, which can complicate matters for their survivors. Regular updates ensure your plan remains relevant and effective.
Following these steps will help you create a comprehensive estate plan that reflects your wishes and protects your loved ones. Next, we’ll explore how to avoid probate in California, a crucial step in streamlining the estate transition process.
Avoiding Probate in California
Probate can be a lengthy and expensive process. It involves proving in court that a will is valid, inventorying a deceased person’s assets, paying debts and taxes, and distributing the remaining property as directed by the will or state law. Fortunately, there are ways to avoid this cumbersome process in California.
Understanding the Probate Process
Probate is a court-supervised procedure that can take months, or even years, to complete. It often involves court fees and attorney fees, which can eat into the value of the estate. In California, probate is required for estates valued over $184,500 as of 2024. If the estate is below this threshold, a simplified process may be available.
Avoiding Probate
Avoiding probate means your assets can be transferred to your beneficiaries without the need for court involvement. Here are some ways to achieve this:
Name Beneficiaries: For certain accounts like retirement or life insurance, you can name beneficiaries directly. Upon your death, these assets go straight to the named individuals, bypassing probate.
Joint Ownership: Holding property jointly with rights of survivorship allows the surviving owner to automatically inherit the property. This is common among spouses.
Transfer on Death (TOD) Deeds: A TOD deed allows you to name a beneficiary who will inherit your real estate upon your death, without the need for probate.
Living Trusts: A living trust is one of the most effective tools for avoiding probate. By placing assets in a trust, they can be transferred directly to your beneficiaries upon your death, without court involvement.
The Role of Trusts
Trusts are powerful tools in estate planning. They can help avoid probate, manage taxes, and provide for beneficiaries according to your wishes. Here’s a quick look at how they work:
Living Trusts: These allow you to manage your assets during your lifetime and specify how they should be distributed after your death. They are flexible and can be modified as your circumstances change.
Irrevocable Trusts: Once established, these cannot be changed. They offer more protection from estate taxes and creditors but require careful planning.
Testamentary Trusts: Created through a will, these become effective upon your death. They don’t avoid probate but can offer control over how assets are distributed to beneficiaries.
Consulting with an Attorney
Navigating the complexities of estate planning and probate in California requires expert guidance. Attorneys specializing in estate planning can help you choose the right strategies to avoid probate and ensure your assets are distributed according to your wishes. Legal fees in California can range from $250 to $1,000 per hour, reflecting the complexity and importance of the work involved.
By taking proactive steps, you can simplify the transition of your estate, save on costs, and provide peace of mind for your loved ones.
Next, we’ll dig into the tax considerations you must keep in mind while planning your estate.
Tax Considerations in Estate Planning
When planning your estate, taxes can significantly affect the assets you leave behind. Understanding estate taxes, inheritance taxes, and effective tax strategies is crucial for preserving your wealth.
Estate Taxes in California
In California, there is no state estate tax, which is a relief for many residents. However, federal estate taxes still apply to estates exceeding $13.61 million as of 2024. This means that if your estate is valued above this threshold, federal estate taxes could take a sizable portion of your assets, up to 40%.
Understanding Inheritance Taxes
Unlike estate taxes, inheritance taxes are paid by the beneficiaries who receive your assets. Fortunately, California does not impose an inheritance tax. Beneficiaries in California can receive their inheritance without worrying about additional state taxes.
Effective Tax Strategies
To minimize tax liabilities, consider these strategies:
Irrevocable Trusts: By placing assets in an irrevocable trust, you remove them from your estate, potentially lowering your taxable estate value. This can be a great way to reduce estate taxes, but these trusts cannot be changed once established.
Gifting: Take advantage of the annual gift tax exclusion, which allows you to gift up to $18,000 per person in 2024 without triggering federal gift taxes. This reduces the size of your estate, potentially lowering estate taxes.
Charitable Donations: Donations to qualified charities can reduce your taxable estate. Not only do you support causes you care about, but you also benefit from tax deductions.
Family Limited Partnerships (FLPs): FLPs allow you to transfer assets to family members at a reduced tax cost, helping to manage estate taxes and maintain control over your assets.
Life Insurance Trusts: By placing a life insurance policy in an irrevocable trust, the proceeds are not included in your estate, reducing estate taxes.
Consulting a Tax Professional
Navigating tax laws can be complex, and they change frequently. Consulting with a tax professional, alongside your estate planning attorney, is essential. They can help you implement the best strategies to minimize taxes and maximize the wealth passed to your beneficiaries.
By understanding and planning for these tax considerations, you can ensure that more of your estate is preserved for your loved ones.
Next, let’s tackle some frequently asked questions about estate planning, including common rules and steps you should be aware of.
Frequently Asked Questions about Estate Planning
Estate planning can feel overwhelming, but breaking it down into questions helps. Here are some common questions to guide you through the process.
What is the 5 by 5 Rule in Estate Planning?
The 5 by 5 rule is a useful tool for those using trusts. It allows a beneficiary to withdraw the greater of $5,000 or 5% of the trust’s assets each year. This flexibility helps beneficiaries access funds without triggering tax consequences or altering the trust’s structure. It’s a great way to ensure financial support while keeping the trust intact.
What are the 7 Steps in the Estate Planning Process?
Creating an estate plan involves several key steps. Here’s a simple breakdown:
Take Inventory: List all your assets, including property, investments, and valuables. This gives you a clear picture of your estate.
Set Goals: Decide what you want to achieve with your estate plan. This might include providing for loved ones, minimizing taxes, or supporting charities.
Draft Essential Documents: Create a will, establish trusts, and set up powers of attorney. These documents ensure your wishes are followed.
Choose a Guardian: If you have minor children, decide who will care for them if you cannot.
Select an Executor: Pick someone you trust to carry out your will and manage your estate.
Review Beneficiaries: Update beneficiaries on insurance policies and retirement accounts to reflect your current wishes.
Regularly Update Your Plan: Life changes, and so should your estate plan. Review it regularly to ensure it still meets your needs.
These steps help create a comprehensive plan that protects your assets and fulfills your wishes.
How Can I Minimize Estate Taxes?
Minimizing estate taxes ensures more of your wealth goes to your beneficiaries. Here are some strategies:
Use Trusts: Trusts can remove assets from your estate, potentially reducing tax liabilities. Consider irrevocable trusts for this purpose.
Gift Strategically: Use the annual gift tax exclusion to give up to $18,000 per person in 2024 without tax consequences. This reduces your taxable estate.
Make Charitable Donations: Donations to charities not only support causes you care about but also reduce your taxable estate.
Consult Professionals: Work with a tax professional and an estate planning attorney to tailor strategies to your situation.
By implementing these strategies, you can significantly reduce the taxes on your estate, ensuring more goes to your loved ones.
Next, we’ll explore how to avoid probate in California and keep your estate matters private.
Conclusion
Estate planning is more than just a set of documents; it’s about securing your legacy and ensuring peace of mind for you and your loved ones. At Brillant Law Firm, we specialize in bespoke strategies custom to meet the unique needs of each client. Our commitment to excellence and unparalleled expertise in California estate law makes us a trusted partner in your planning journey.
Located in Walnut Creek, Saranap, San Miguel, and Castle Hill, California, we understand the nuances of local estate laws and tax regulations. Our team is dedicated to crafting ironclad estate plans that protect your assets, minimize taxes, and reflect your personal wishes.
Whether you’re setting up a living trust, drafting a will, or planning for incapacity, our attorneys are here to guide you every step of the way. We believe in a collaborative approach, working alongside financial planners and tax professionals to create a comprehensive plan that aligns with your goals.
Estate planning doesn’t have to be daunting. With Brillant Law Firm by your side, you can steer the complexities with confidence. Our custom solutions ensure that your affairs are in order, providing you and your family with the security and clarity you deserve.
Ready to take the next step in securing your legacy? Find how our certified specialists can assist you and ensure your estate planning needs are met with precision and care.


